Parameter Robustness Test
Available in the Robustness tab of the Performance window. It answers the most important question once you have found a good strategy: does it only work with exactly these parameters, or also with the values around them?
A strategy that only wins with "CCI of 7 and an exit after 10 bars", and loses with 6 or 11, has not found anything: it has found a coincidence of the past. One that wins with almost every nearby value has found real market behaviour, and will survive a future that is not identical to the past.
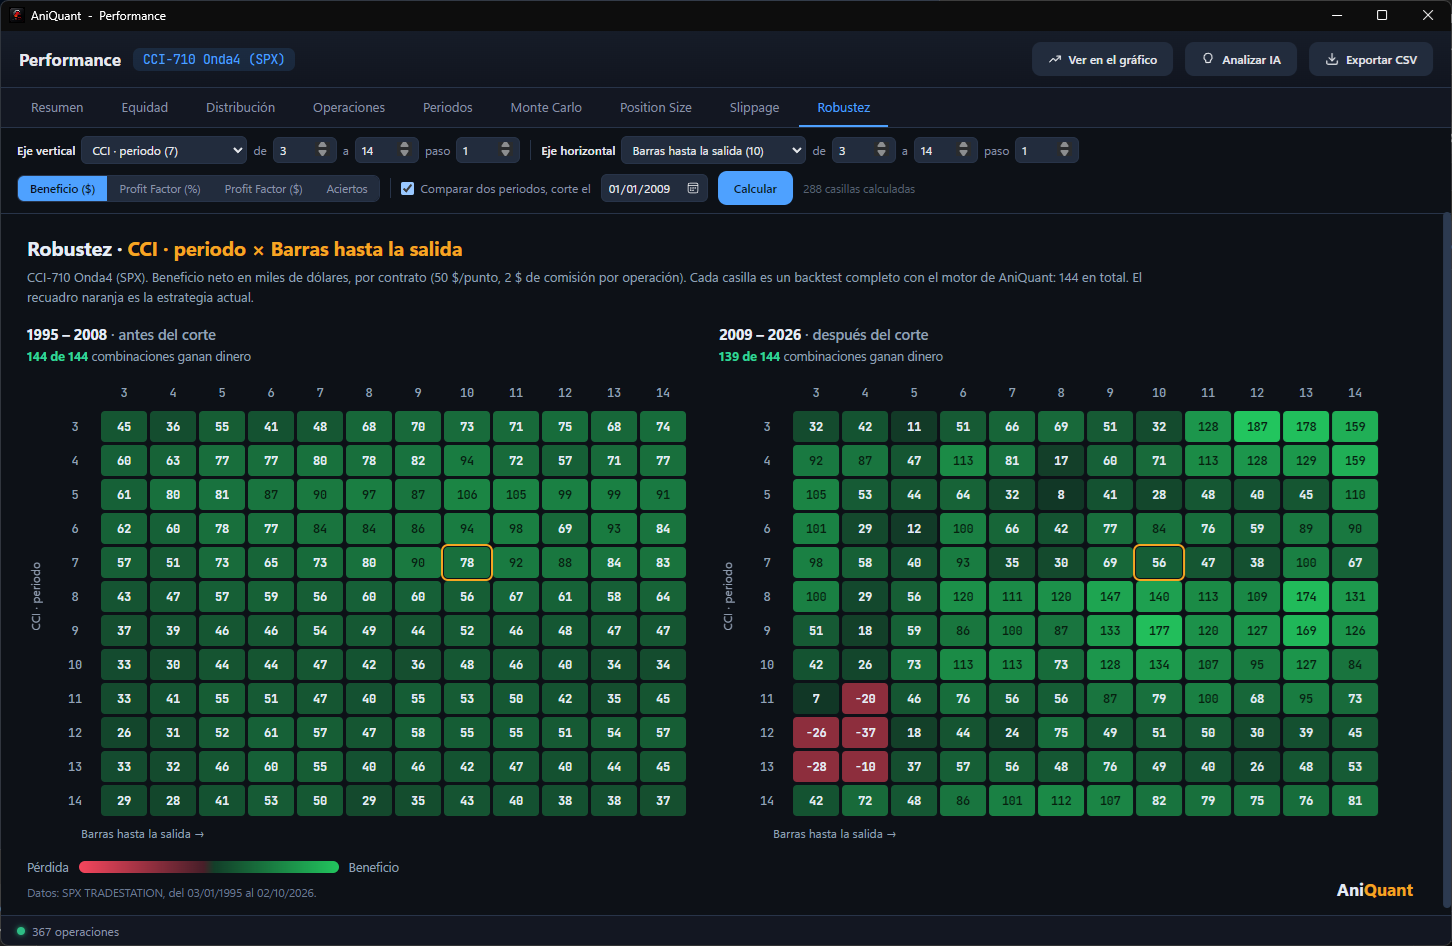
What each cell is
Each cell is a full backtest of the whole strategy, with a different value of the two chosen parameters. The row gives the value of the first, the column the value of the second, and the number is the result of that combination in the chosen metric.
Green when it wins, red when it loses; the stronger, the further from the neutral point. Both panels share the same scale, so they compare at a glance.
Your strategy as it stands. What matters is what surrounds it, not its own number.
Above each panel: how many combinations make money (or beat PF 1, or a 50% win rate). "144 of 144" is a perfect plateau.
Parameters move together
AniQuant detects every parameter of the strategy and links them: the same parameter changes at once in every condition where it appears. That way each cell is a coherent strategy, the one you would actually write with that value.
- ·Indicator period: in CCI-710 the CCI(7) appears in the long entry, in the short entry and compared with itself one bar earlier. Moving to 9 changes all of them to 9.
- ·Threshold: −100 (longs) and +100 (shorts) are a single "±100" parameter. Testing 120 gives −120 for longs and +120 for shorts.
- ·Bars until exit (BarsSinceEntry), maximum bars, take profit and stop loss, when the strategy uses them.
Price series (Close, Close[5]) are not listed: they have no parameter worth sweeping.
Step by step
Comparing two periods: the acid test
With the cutoff date, each cell is split in two: the trades that started before and those that started after. Two maps appear side by side, with the same colour scale.
Use it to separate the period you designed the strategy with from the period it never saw. If the green plateau on the left stays green on the right, the idea has survived the future. If it fades, it was a coincidence of the design period.
The orange box sits inside a wide green plateau. Neighbouring values win too: the strategy does not depend on hitting the exact parameter.
The box is an isolated peak surrounded by red or pale green. Any small change destroys the result: it is luck, not edge.
If the plateau is wide, take a value from its centre: if the market drifts a little, you will still be inside the good zone.
Details worth knowing
- ·Profit is per contract, with the symbol's point value and commission. Above $10,000 the map shows it in thousands of dollars.
- ·Profit Factor (%) weighs every trade the same whatever the price level (the one used in rankings); Profit Factor ($) is the one TradeStation or AmiBroker report. See the Summary tab.
- ·A grey cell with "—" has fewer trades than the required minimum: it is not rated.
- ·The periods of a comparison may have different lengths (14 years against 18 in the picture): compare how many cells win and where the plateau is, not the absolute figures.
- ·The map uses the same engine as the backtest: the orange cell matches the result in the Summary tab.
Equity tab: in and out of sample
- ·The out-of-sample (OOS) stretch is shaded and labelled («IN-SAMPLE» / «OUT-OF-SAMPLE (OOS)»), AQ Genesis strategies included.
- ·A grey buy-and-hold 1 contract line from the first trade, for comparison. Turn it on with its checkbox in the legend; it is hidden while Position Size is active.
- ·Underneath, a panel with the drawdown of both curves.
The Summary tab tells apart two Profit Factors: (%), computed with each trade's percentage (the one every ranking uses), and ($), gains ÷ losses in money, the one TradeStation and AmiBroker report. With prices that rise a lot they can differ considerably.
AniQuant can be tried free for 14 days, with every module and no card. If you have the book, 30.